Article 38 · Europe
France now pays more to borrow than Italy, and nothing automatically stops the slide
France borrows by selling bonds to investors, and the extra interest it pays over Germany has passed Italy's. The European Central Bank has a rescue tool, but it has no set trigger.
What the spread is and why it matters
Governments borrow by selling bonds. Investors buy them and demand an interest rate, called the yield. The more worried they are, the higher the yield they ask for. The usual way to read that worry is the spread, which is the gap between one country's yield and Germany's. Germany is treated as the safest borrower in the euro area.
France's 10-year bond is called the OAT, and the German one is called the Bund. A basis point is one hundredth of a percentage point. On October 12th, 2026 the French spread closed at 139.5 basis points, wider than the 107 basis points Italy paid on October 9th.
Italy carries public debt of 138.6% of its economy, and France's premium has now passed Italy's. A wider spread raises what the state pays on every new bond it sells, so the number feeds straight into the budget.
The question is who steps in if the selling gets worse. The European Central Bank (ECB), the central bank for the countries that use the euro, has a bond-buying tool for that case. It has no automatic trigger. The rest of this article explains what it does depend on.
What the market did
Figure 1 shows how fast the gap grew. The French spread closed at 81.7 basis points on August 27th. By the close on October 2nd it was 146.9 basis points. Over the previous year it had averaged 76.2 basis points.
The selling was specific to France. In the week to October 2nd the French 10-year yield rose 14 basis points while the German yield fell 12.5 basis points, according to the analyst David Annen.
The spread did not stay at its peak. It closed at 139.5 basis points on October 12th. Data from the Idéal Investisseur site, which compiles Banque de France and Bundesbank closing figures, show it back at 153.4 basis points on October 29th, 2026.
The 2011 euro crisis is the usual comparison. On the same closing series the spread peaked at 225.1 basis points on November 17th, 2011. The current level is lower.
French 10-year spread over Germany
Basis points, closing series
Why France is under pressure
Prime Minister Sébastien Lecornu leads a minority government. It presented its 2027 budget on October 1st. The budget cuts the deficit only to 5.0% of economic output from 5.4%, and public debt still rises to 121.7% from 119.3%.
Interest is the fastest-growing cost. ING, a bank whose analysts follow European bonds, projects interest payments rising by 12 billion euros to 91 billion euros in 2027. The state also plans to borrow a record 340 billion euros that year.
The buyers have changed too. The economist Hanno Lustig says French insurers and pension funds held about 25% of the state's negotiable debt in 2014 and hold under 11% today. Rating agencies, firms that grade a borrower's credit, have also moved. Scope cut France to A+ from AA- in September. Fitch holds it at A+ with a stable outlook. Moody's rates it Aa3 with a negative outlook.
Why the ECB has no automatic trigger
The ECB created the Transmission Protection Instrument (TPI) on July 21st, 2022, after an Italian bond selloff. Its stated aim is to counter "unwarranted, disorderly market dynamics". It has never been used.
The TPI has no spread level that opens it. Instead the Governing Council, the ECB's top decision body, applies a list of criteria. The first is that the country follows the EU's budget rules. ING reads that as requiring, at a minimum, full adoption of the 2027 French budget.
France's case is open to argument. The European Commission, the EU's executive arm, found on June 3rd, 2026 that France had taken effective action on its deficit. Annen reads that as meeting the fiscal test today. ING does not.
Officials point the same way as ING. Banque de France governor Emmanuel Moulin, who sits on the Governing Council, said: "There are mechanisms that are linked to very critical situations on markets that prevent the proper transmission of monetary policy. But these mechanisms are only used if measures are taken at a national level." ING quoted him. ECB President Christine Lagarde told euro-area finance ministers on October 8th that the ECB has tools, and that they carry conditions.
Monetary policy makes early buying harder. The ECB raised its deposit rate to 2.50% in September, and euro-area inflation reached 3.8% that month. Rabobank expects the ECB to try words first, then a pause in shrinking its bond holdings, before any purchase.
Where Italy and Spain come in
Stress spread beyond France in early October. ING strategists reported that Italian and Greek spreads widened by almost 15 basis points during the French selloff. Italy's spread made its biggest daily jump since 2020 on October 1st, then fell to 107 basis points by October 9th from 130 basis points a week earlier.
That is why Italy matters to the ECB. ING expects pressure on the central bank to build if French stress pushes up yields in other heavily indebted countries. Spain called a snap election for November 29th, and its spread stood near 64 basis points on October 5th.
Until the selling reaches those countries, the ECB has less reason to act. For investors, the Italian spread is the better gauge of whether the stress is spreading.
Who decides
Three people hold much of the answer, as pictured below. The budget decides the first condition, and the ECB decides the rest. Lecornu can pass the budget under Article 49.3 of the constitution, which skips a vote unless a no-confidence motion succeeds. The Commission's opinion on the draft budget is due by November 30th.
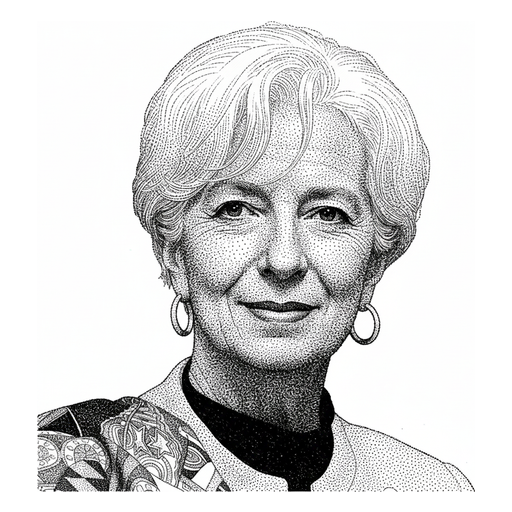
Christine Lagarde
President, European Central BankTold finance ministers on October 8th that the ECB has tools for unwarranted market moves, with conditions attached.
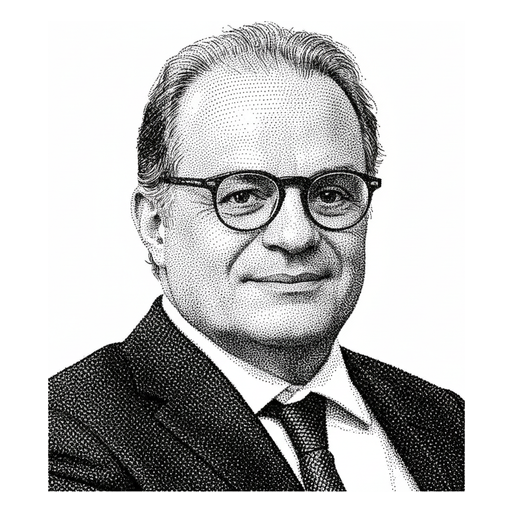
Emmanuel Moulin
Governor, Banque de FranceHas said the backstop is used only if measures are taken at national level.
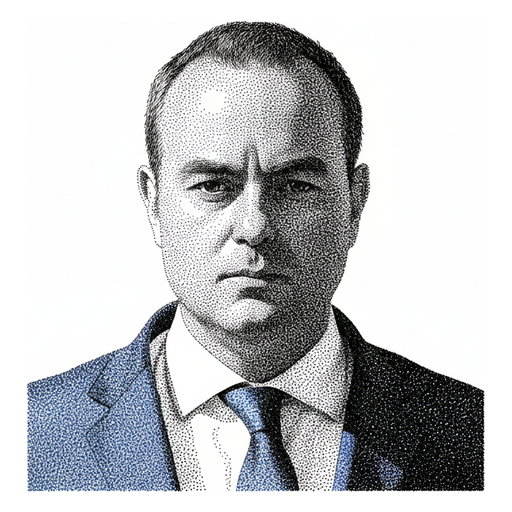
Sébastien Lecornu
Prime Minister of FranceLeads a minority government that presented the 2027 budget on October 1st.
The other reading
Robin Brooks of the Brookings Institution argues the ECB will be forced to step in despite its rules, because it capped Italian and Spanish yields in 2022. The ECB has itself said its criteria will be "dynamically adjusted".
Maartje Wijffelaars of Rabobank argues the other way. She says most of the widening appears to be over, because investors see France as too big to fail and the crisis tools exist.
Vektora's October 13th analysis answers both on sequence. Brooks may be right about where this ends, but the route still runs through a budget vote and a Commission opinion. Vektora expected the ECB to stay out of the French market through 2026 while the spread traded between 100 and 150 basis points. The October 29th reading of 153.4 basis points is above that range.